The easiest saving to overestimate is the time spent on the visible step. Copying a record may take four minutes, but an automated record still needs checking and occasional repair. Build your estimate from the work that remains.
Use a comparable baseline
Measure several ordinary working days. Record volume, handling time, corrections and waiting separately. A task that waits overnight is not necessarily eight hours of labour. Include the same scope before and after automation, such as opening the source, entering details and checking the result.
Keep rare heavy cases visible. A weekly average can conceal a process that works for simple inputs but costs an hour to fix unusual ones.
A worked example with assumed numbers
This example is hypothetical and is not a measured Set It Once or customer result.
| Monthly item | Assumption |
|---|---|
| Manual handling | 120 records × 4 minutes = 480 minutes |
| Automated-result review | 120 × 1 minute = 120 minutes |
| Failure recovery | 6 cases × 8 minutes = 48 minutes |
| Maintenance | 60 minutes |
| Net time released | 480 minus 120 minus 48 minus 60 = 252 minutes, or 4.2 hours |
At an assumed internal time value of €30 per hour, 4.2 hours represents €126 in capacity. With an assumed €25 monthly tool cost, the estimated recurring capacity value is €101. This is not necessarily cash saved: wages may remain unchanged and freed time may not generate sales.
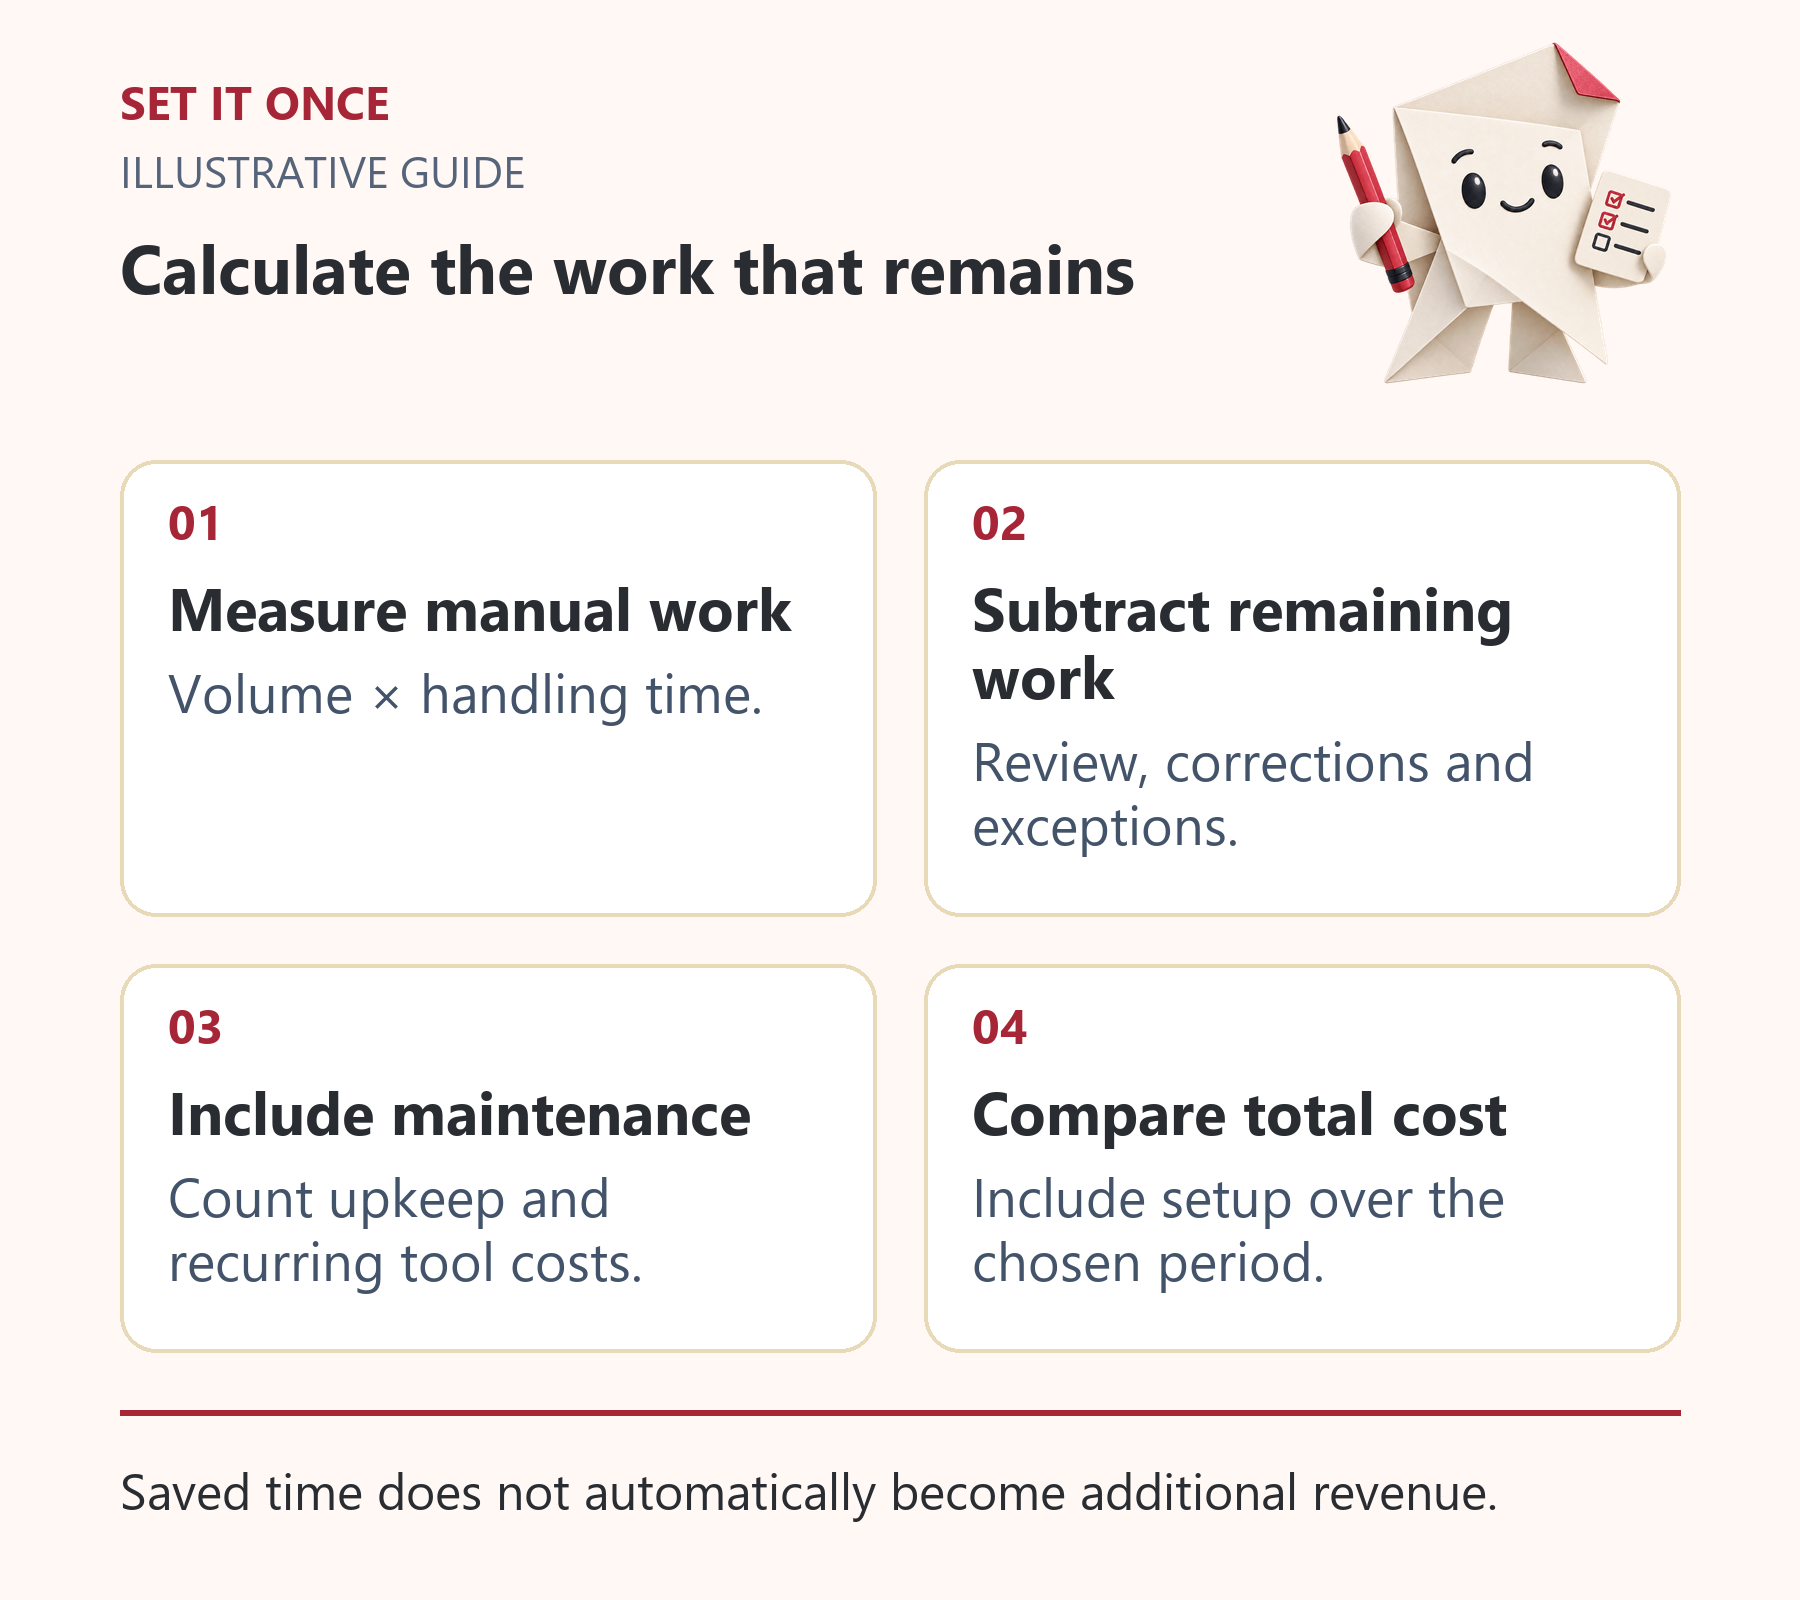
Original illustrative guide: Set It Once. Saved time does not automatically become additional revenue.
Read the text version
- Measure manual work. Volume × handling time.
- Subtract remaining work. Review, corrections and exceptions.
- Include maintenance. Count upkeep and recurring tool costs.
- Compare total cost. Include setup over the chosen period.
Include setup and uncertainty
If the assumed setup costs €600, dividing by €101 gives about six months to recover that amount in estimated capacity value. This calculation is only meaningful if the released capacity is useful and recurring. It is not a financial return guarantee.
Stress-test the estimate. If review rises to two minutes per record, net time falls to 132 minutes, or 2.2 hours. At the same assumed rate and tool cost, recurring capacity value falls to €41. The apparent six-month case becomes roughly fifteen months. Review time can change the decision more than software price.
Fill in your pilot worksheet
Monthly volume: __. Manual minutes: __. Review minutes: __. Failure count and recovery minutes: __. Monthly maintenance: __. Tool cost: __. Setup cost: __. Useful use of released time: __. Pilot owner: __.
Run a limited pilot and replace assumptions with observations. Compare corrections, missed records and workload as well as time. If the process removes effort but creates hidden risk, improve it before increasing volume.
Choose a decision date. Continue, adjust or stop based on the measured result; do not keep a subscription solely because setup has already been paid for.
Find the volume at which the process becomes worthwhile
Use the assumptions in the example above to separate variable work from fixed upkeep. Four minutes of manual work minus one minute of review gives three minutes released per record. If five per cent of records need eight minutes of repair, expected recovery adds 0.4 minutes per record. The resulting contribution is 2.6 minutes per record before the fixed monthly maintenance hour.
At the same assumed €30 hourly capacity value, 2.6 minutes represents €1.30 per record. The fixed maintenance hour and €25 tool cost total €55 in monthly capacity and tool cost. Dividing €55 by €1.30 suggests roughly 43 records per month to exceed that recurring total. This is a planning threshold under those assumptions, not cash profit, and it excludes recovery of setup.
Stress-test the assumption most likely to change
If review takes two minutes instead of one, contribution drops to 1.6 minutes, or €0.80 per record at the assumed rate. The recurring threshold becomes about 69 records. At 120 records, subtracting the €55 fixed total leaves €41 of monthly estimated capacity value. The same €600 setup would then take about 14.6 months to recover in that capacity measure, compared with about six months in the first scenario.
Before buying, ask what happens at lower volume, higher exception rates and a month when the maintainer is unavailable. Include usage-based charges in the variable part if they rise with records. If the benefit disappears under a plausible change, use a smaller pilot or simplify the workflow before committing to the full build.
Distinguish capacity, avoided cost and revenue
Released staff time is capacity. It becomes avoided cash cost only when a real expense is reduced or avoided, such as paid overtime that is no longer needed. Additional revenue requires another chain: demand exists, the released time is used to serve it, and the contribution exceeds the additional cost. Do not add hypothetical sales to capacity savings without identifying that mechanism.
Keep a pilot ledger of observed volumes, review minutes, repairs and upkeep. Compare those observations with the assumptions, then decide whether to continue, redesign or stop. That decision is more useful than a precise-looking return percentage built on unmeasured inputs.
Take one practical next step
If this is a problem in your team, explore AI consultation. Describe one task, the software you use and the result you need. Scope and terms are agreed before work begins.
Quick answers
Frequently asked questions
Is time saved the same as money saved?
No. Released working time is capacity. Cash savings depend on actual changes to spending, and revenue depends on how that capacity is used.
Should setup cost be included?
Yes, when comparing the total decision. Keep one-off setup separate from recurring costs so you can see both.
What if the pilot volume is unusually low?
Record that limitation and compare representative periods. Do not extrapolate a quiet week without checking normal demand.
About the author
Martin Iliev
Martin builds Set It Once to help people spend less time on repeated work. His guides explain what you can try, how to check the result and where the limits are.
More about Martin